

Key Takeaways
- Homeowners insurance covers sudden roof damage from wind, hail, fire, or a falling tree limb, not gradual wear and tear.
- Report damage quickly, document everything, and make temporary repairs to protect your claim.
- Whether your policy pays Actual Cash Value or Replacement Cost Value, plus your deductible, decides how much of a new roof you pay yourself.
Storm damage leaves more than just shingles scattered, it leaves homeowners facing a maze of insurance rules and paperwork. You want clear answers, fast repairs, and the assurance that your policy will actually cover what you need. This guide breaks down the roof insurance claim process into simple, practical steps so you can move forward with confidence instead of confusion.
Understanding roof insurance basics
Homeowners insurance is designed to protect you from sudden and accidental damage, not gradual wear and tear. When it comes to your roof, this usually means coverage for events like wind, hail, fire, lightning strikes, or a tree limb crashing down during a storm.
The key word is unexpected. If shingles are curling from age or a small leak has worsened over years, insurance will not step in. But if a hailstorm shatters your shingles overnight, that’s the kind of loss most policies are built to cover.
It’s also helpful to understand what’s being protected. Your policy generally covers the structure of your home, this includes the roof itself, the walls, and other permanent fixtures. Separate sections of your policy may also cover personal property (your belongings inside the home) and even provide support for additional living expenses if damage leaves your house temporarily unlivable. While these categories work together, the roof falls squarely under structural coverage.
Another important distinction is how policies define the value of your roof. Some pay only the current, depreciated value (Actual Cash Value), while others pay for a full replacement (Replacement Cost Value). This difference can drastically change what you owe out of pocket, so knowing which type you have before filing a claim can prevent surprises later.
At its core, roof insurance is there to help you recover quickly after a sudden loss not to upgrade an aging roof. Understanding these basics sets the stage for filing a successful claim.
Filing Your Claim and Getting Paid
Key steps in filing a roof insurance claim
Filing a roof insurance claim isn’t complicated when you know the right steps to take. In fact, roof-related issues account for nearly one in five homeowners insurance claims each year, making them one of the most common types of claims filed. Taking a systematic approach can save you time, reduce stress, and improve the chances of approval.
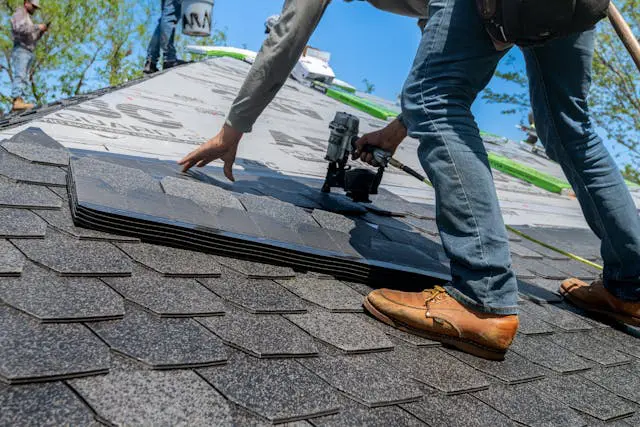
Here are the essentials to focus on:
- Act quickly: Call your insurance company as soon as you suspect storm damage. Delays can lead to worsening problems, like leaks that spread, which may give your insurer grounds to deny or limit coverage. Prompt reporting shows responsibility and ensures an adjuster is assigned before more damage occurs.
- Document everything: Photos, videos, and written notes are your strongest evidence. Capture wide shots of the entire roof and close-ups of visible damage. Keep receipts for past roof work and gather any inspection reports. The clearer your records, the easier it is for the adjuster to confirm damage is storm-related rather than from age.
- Temporary repairs: If your roof has holes or missing shingles, make safe, temporary fixes to prevent further damage. Cover exposed areas with tarps or have a contractor perform emergency patches. Always save receipts, these expenses are often reimbursable under your policy.
It’s important to remember that while a roofing contractor can inspect the damage and even meet the adjuster to explain their findings, only the insurance adjuster has the authority to approve or deny your claim. Contractors are valuable advocates, but the final decision rests with your insurer.
By moving quickly, keeping thorough records, and preventing additional harm, you strengthen your case and avoid common setbacks that delay or reduce payouts.
How your policy type shapes your payout
Not all roof insurance policies pay the same way. The type of coverage you have will determine whether you’re left covering a large portion of costs yourself or if most of the replacement is paid for. Here’s what you need to know.
Actual Cash Value (ACV) policies
An Actual Cash Value policy reimburses you for the current value of your roof, factoring in depreciation. This means the older your roof, the smaller the payout. For example, imagine you have a roof that cost $12,000 to install but is now 15 years old with a 25-year life expectancy. Under an ACV policy, the insurer may calculate it as halfway through its lifespan and only reimburse about $6,000 leaving you to cover the rest. This option can keep premiums lower, but it often leads to higher out-of-pocket expenses after a storm.
Replacement Cost Value (RCV) policies
A Replacement Cost Value policy covers the cost of restoring your roof to a brand-new version of itself. The payout typically comes in two parts: first, the insurer issues a check for the ACV portion, then holds back the “recoverable depreciation.” Once the roof is replaced and proof of completion is provided, you receive the second payment. For homeowners, this approach offers far greater financial protection, which is why RCV policies are often preferred despite slightly higher premiums. The main limitation is that coverage only restores what you had before upgrades, like switching to premium shingles, are your responsibility.
Deductibles and out-of-pocket costs
Regardless of policy type, every claim comes with a deductible the amount you must pay before insurance covers the rest. Understanding these costs upfront prevents surprises. Use this quick checklist before filing a claim:
- Review deductible amount on policy – Confirm whether it’s a flat dollar figure or a percentage of your home’s value.
- Confirm whether upgrades are covered – Most policies exclude enhancements, so be prepared to pay for improvements yourself.
- Clarify if local codes may increase costs – Code requirements, like ventilation or underlayment upgrades, may add expenses not fully covered by standard policies.
Knowing whether your policy is ACV or RCV and how deductibles affect the final payout can help you budget realistically and avoid sticker shock during the claims process.
After Approval: Contractors, Red Flags, and Support
Choosing the right contractor after approval
Once your roof insurance claim is approved, the next critical step is selecting the right contractor. This isn’t just about finding someone who can replace shingles, it’s about choosing a professional who understands the insurance process and ensures the work aligns with your claim.
Start by focusing on local, licensed contractors. Local companies are easier to verify, more accountable if issues arise, and less likely to disappear after the job is done. Next, confirm that the contractor has specific experience handling insurance claims. Roofing companies familiar with the process can read your claim documents, catch missing line items, and communicate effectively with your insurer.
Equally important is what not to do: don’t sign paperwork before your claim is approved. Some contractors push early contracts to lock in your business, but doing so can create problems if your claim is denied or requires adjustment. Another red flag is any company that offers to waive or “cover” your deductible this is considered insurance fraud and could leave you liable.
Here’s a quick checklist to guide your decision:
- License: Verify the contractor is properly licensed in your state.
- References: Ask for recent customer reviews or completed project photos.
- Insurance knowledge: Ensure they’ve worked directly with insurance claims before.
- Willingness to meet adjuster: A good contractor will walk the roof with your adjuster to advocate for you.
Choosing carefully at this stage helps protect your payout, ensures code compliance, and reduces the risk of poor workmanship that could cost you more in the long run.
Spotting red flags and common claim pitfalls
Even after your claim is approved, mistakes and bad actors can cost you money or void your coverage. In fact, insurance fraud is estimated to cost Americans more than $80 billion each year, and roofing scams are a major contributor. Recognizing warning signs early helps you protect both your home and your payout.
Watch out for these red flags:
- Contractors offering to “cover” your deductible
This practice may sound like a discount, but it’s actually insurance fraud. If discovered, it could jeopardize your claim and expose you to legal penalties. - Pressure to sign contracts before claim approval
Reputable contractors wait until your insurance company confirms coverage. Signing too early locks you into a contract that may not align with your final payout, leaving you stuck with unexpected costs. - Lowball quotes that undercut quality materials
Some contractors lure homeowners with unusually low bids. These often mean cutting corners with cheaper materials or rushed labor, which can shorten your roof’s lifespan and void warranties. - Estimates missing key items
A legitimate insurance estimate should include all necessary line items labor, disposal fees, permits, and compliance with local building codes. Missing costs can leave you paying out of pocket for essentials that should have been covered.
The best safeguard is vigilance. Take time to review documents, ask questions, and compare estimates against your policy details. If something feels off like a price that’s too good to be true it probably is. By staying alert to these pitfalls, you keep your claim on track and ensure your roof is repaired the right way.
How Farmer Brown helps
Farmer Brown is not an insurance company. We are an independent insurance broker: we compare policies from multiple carriers to find the best price and coverage for each client.
That work matters before a storm ever hits. Whether your policy pays Actual Cash Value or Replacement Cost Value, and whether your deductible is a flat amount or a percentage of your home’s value, decides how much of a new roof you pay out of pocket. We review those details with you and shop several carriers so your coverage fits your home and your budget.
If you are not sure what your current policy would pay on a roof claim, we can review it with you and compare it with options from other carriers.
Takeaway
Roof insurance claims can feel overwhelming, especially when you’re already dealing with the stress of storm damage. But when you know your policy, document damage carefully, and choose a trustworthy contractor, the process becomes far more manageable. Each step you take whether it’s saving receipts for temporary repairs or double-checking that your contractor doesn’t cut corners protects your home and your finances.
Think of the process as a checklist: review your policy type, confirm your deductible, gather evidence, and bring in a reliable professional once your claim is approved. These small, intentional actions prevent costly mistakes and keep your claim on track.
The most important thing is to act quickly. Insurance companies expect prompt reporting, and delays can give them grounds to reduce or deny coverage. If you suspect damage, don’t wait to start the process right away.
By approaching your claim with clarity and preparation, you’ll not only safeguard your home but also reduce stress during what could otherwise be a confusing time. Use the guidance in this article as a reference point for your own workflow, and you’ll move through the claims process with greater confidence.
Roof Insurance Claim FAQs
No. Homeowners insurance covers sudden and accidental damage, such as wind, hail, fire, lightning, or a tree limb falling during a storm. Shingles curling from age or a small leak that worsened over years are wear and tear, which policies do not cover.
An Actual Cash Value policy pays the current, depreciated value of your roof, so the older the roof, the smaller the payout. A Replacement Cost Value policy pays to restore the roof to a brand-new version of itself, usually in two payments: the ACV portion first, and the recoverable depreciation once the work is done.
No. Signing before approval can lock you into a contract that does not match your final payout. Reputable contractors wait until your insurance company confirms coverage.
No. Offering to waive or cover your deductible is considered insurance fraud. It can jeopardize your claim and expose you to legal penalties.