

Key Takeaways
- High winds, heavy rain, and falling debris make the roof the most exposed part of a home when storms strike.
- Homeowners insurance usually covers sudden storm damage such as wind, hail, or falling debris, but not normal wear and tear.
- Inspect and reinforce your roof before storm season, and document damage quickly and safely after a storm.
Storms can turn a secure home into a costly repair project overnight. Roofs take the brunt of high winds, heavy rain, and falling debris, making them especially vulnerable. This guide will show you how to strengthen your roof against severe weather, understand what your insurance really covers, and steer clear of mistakes that could delay or reduce your claim.
Why roofs are vulnerable in severe weather
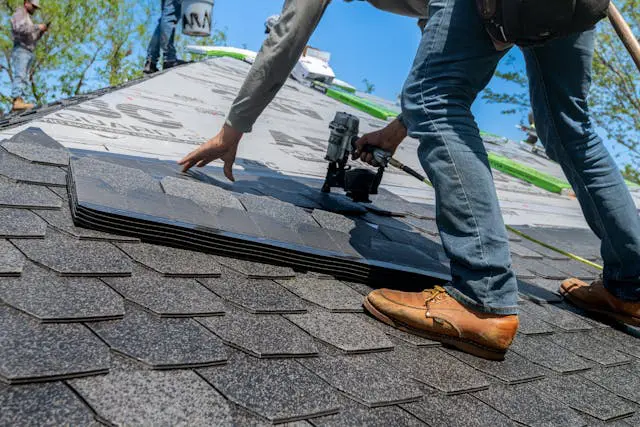
Your roof is the first line of defense against the elements, but it is also the part of the home most exposed when storms strike. High winds can lift or tear shingles, heavy rain can seep into weak spots, and falling branches can puncture even well-built structures. Over time, these threats combine to make the roof one of the most common sources of insurance claims after severe weather.
A roof does not need to collapse completely to create problems. A few missing shingles or a small leak can quickly escalate into water damage, mold growth, or structural weakening inside the home. Once moisture enters, repair costs increase dramatically, often spreading beyond the roof to ceilings, insulation, and walls. For homeowners, this means a small oversight before a storm can result in thousands of dollars in unexpected repairs.
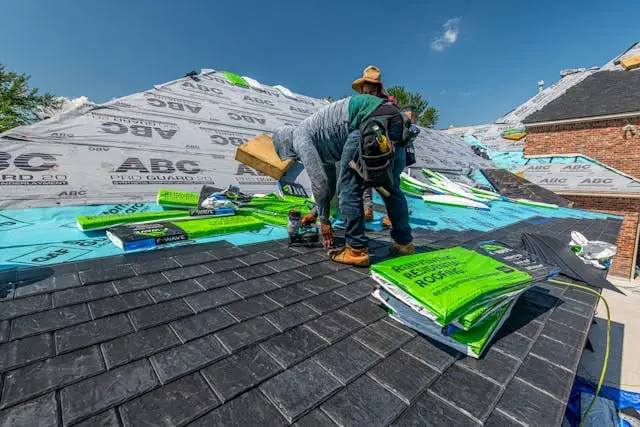
Older roofs are especially at risk because materials naturally degrade over time. Asphalt shingles may lose granules, sealants dry out, and flashing becomes loose. When a storm hits, these weak points give way more easily. Even new roofs are not immune if they are poorly maintained or were not installed to withstand local weather conditions.
Understanding why roofs are vulnerable is the first step in protecting your investment. By recognizing common risks and addressing them early, homeowners can reduce the chances of major damage and ensure their insurance coverage applies when it matters most. Prevention paired with preparation is what keeps a roof strong through every season.
How insurance covers roof damage
Homeowners insurance is designed to protect against sudden and unexpected losses, and roof damage often ranks among the most common claims. Policies typically cover roofing insurance claims for storm damage and harm caused by storms such as wind, hail, or falling debris. This protection ensures that when extreme weather strikes, you are not left to manage the financial burden of major repairs on your own.
Coverage, however, comes with important limitations. Most policies exclude normal wear and tear, meaning damage that develops slowly over time is not covered. If a roof is nearing the end of its life span or has not been properly maintained, insurers may reduce or deny payment. Understanding these exclusions is critical because a storm that damages an aging or neglected roof may leave the homeowner responsible for much of the cost.
The type of payout also matters. Some insurers offer actual cash value, which subtracts depreciation from the settlement. Others provide replacement cost coverage, which pays for a new roof of similar quality without deducting for age. Knowing the difference between these two options can mean the difference between a partial payout and full restoration.
Costs can add up quickly. The average homeowners insurance claim for roof damage runs into thousands of dollars, highlighting why clarity about coverage is so important. Deductibles also play a role, and higher deductibles may reduce premiums but leave more expense on the homeowner’s side during a claim.
When reviewing a policy, homeowners should confirm exactly what storm events are covered, check the deductible, and note whether their roof is insured at cash value or replacement cost. This knowledge provides peace of mind and ensures fewer surprises when the next storm hits.
Prevention, Storm Response, and Common Mistakes
Prevention strategies every homeowner should use
Storm damage is not entirely avoidable, but preparation can greatly reduce the risk. By taking proactive steps, homeowners can strengthen their roofs, extend their lifespan, and increase the chances of a smooth insurance claim when bad weather arrives.
Regular inspections and maintenance
A roof that receives consistent attention stands a far better chance against storms. Homeowners should schedule at least one professional inspection a year and follow up with visual checks after major weather events. Small issues such as cracked shingles, loose flashing, or clogged gutters may not seem urgent but can quickly worsen under heavy rain or strong winds. Catching these problems early saves both time and money. For example, a homeowner who notices and replaces just a few missing shingles before storm season may prevent water from entering and damaging an entire ceiling.
Reinforcing weak points
Not every roof is built to handle severe conditions, but upgrades can make a difference. Installing impact resistant shingles reduces the chance of hail punctures, while hurricane straps and clips can help secure the roof structure to the walls. Sealing edges and valleys where water commonly seeps in provides another layer of defense. These reinforcements not only protect the home but can also lower insurance premiums in some cases because they demonstrate reduced risk.
Clearing debris and drainage
A clean roof and drainage system is a strong roof. Gutters and downspouts that are free of leaves allow water to move away quickly, preventing pooling and leaks. Overhanging branches should be trimmed to avoid falling limbs during high winds. Homeowners can use a simple checklist: keep gutters clear, check that downspouts extend several feet from the foundation, and cut back any trees that lean over the roof. These straightforward steps limit common hazards that cause significant storm damage.
Preparation requires effort, but it pays off in reduced damage, easier insurance claims, and long term protection. A roof that is inspected, reinforced, and kept clear of debris is far more likely to withstand the worst storms nature delivers.
Steps to take after a storm hits
When a storm passes, the way you respond can determine how smoothly repairs and insurance claims move forward. Acting quickly, while keeping safety first, ensures that damage is properly documented and prevents small issues from becoming larger problems.
Begin with a safety check. Avoid climbing onto the roof immediately after the storm, as wet surfaces and loose debris can make it dangerous. Instead, walk around the property from the ground and note visible signs of damage such as missing shingles, sagging gutters, or fallen branches.
Documentation is the next priority. Take clear photos of all visible damage from multiple angles and, if safe, capture pictures of the interior where water may have leaked through. Save receipts for any temporary fixes you purchase, such as tarps or plywood, since insurers often reimburse reasonable emergency expenses.
Contact your insurance company promptly to start the claims process. Provide the photos, receipts, and a clear description of what occurred. Quick communication reduces delays and helps establish an accurate timeline of the damage.
Be cautious when seeking repairs. Only work with licensed and insured contractors, and avoid anyone who pressures you into signing agreements before your claim is approved. Reliable contractors will provide clear estimates and wait for insurance confirmation before beginning major work.
A simple checklist can guide homeowners after a storm: photograph all visible damage, save receipts for temporary fixes, notify the insurer quickly, and choose trustworthy contractors. These steps keep the process organized and make recovery less stressful.
Red flags and common mistakes to avoid
Even with good insurance and careful preparation, many homeowners run into problems after a storm. Missteps in the claims process or falling for scams can delay repairs and increase out of pocket costs. Recognizing red flags early helps protect both your home and your wallet.
One of the most common mistakes is accepting offers from contractors who promise to cover your deductible. While this may sound appealing, it is considered insurance fraud and can void your claim. Homeowners should be wary of anyone suggesting ways to manipulate the process for quick savings.
Another warning sign is pressure to sign contracts before the insurance company has approved the claim. Unscrupulous contractors sometimes rush homeowners into agreements that commit them to inflated costs or unnecessary repairs. Waiting for official approval ensures that the scope of work matches what the insurer will cover.
Low repair quotes can also be a problem. While everyone wants to save money, quotes that are far below average often indicate poor workmanship or hidden fees. Choosing a contractor based only on the lowest number may lead to incomplete or unsafe repairs that cost more to fix later.
Insurance fraud is not rare, and it accounts for billions in losses each year, which makes insurers extra cautious during the claims process. Homeowners should stay organized, document every step, and ask questions whenever something feels unclear.
Quick checks to keep in mind:
- Contractors offering to cover your deductible
- Pressure to sign paperwork before claim approval
- Quotes that are unusually low compared to others
Avoiding these pitfalls keeps your claim on track and ensures repairs are handled properly. Staying vigilant after a storm is just as important as preparing before it.
Overlooking roof age in claims
Insurers often review the age of a roof when processing claims. Older roofs may receive reduced payouts or be excluded from full coverage if wear and tear is the main factor. Ignoring how roof age affects coverage can leave homeowners with unexpected costs.
Misunderstanding storm damage coverage
Not all storm damage is treated equally in a policy. Wind and hail may be covered, while flooding is often excluded. Filing a claim without checking the exact terms can result in delays or denials, so homeowners must know the details before submitting paperwork.
Neglecting roof maintenance before storms
Routine maintenance is essential, yet many homeowners overlook it until after damage occurs. Insurers can deny or reduce claims if poor roof maintenance is a contributing factor. Keeping records of inspections and small repairs provides proof that the roof was cared for properly.
Confusing hail damage with normal wear
Hail damage can look similar to natural aging, but insurers distinguish between the two. Homeowners who cannot provide clear documentation may struggle to prove their case. Professional inspections after hailstorms help create a record that supports legitimate claims.
Underestimating the impact of water damage
Water damage often starts small but spreads quickly through insulation, ceilings, and walls. Homeowners who fail to act immediately or document leaks thoroughly risk claim denials. Quick photos, receipts for temporary fixes, and prompt reporting are essential to ensure water damage is covered.
How Farmer Brown helps
Farmer Brown is not an insurance company. We are an independent insurance broker: we compare policies from multiple carriers to find the best price and coverage for each client.
Before storm season, we can review your policy with you so you know which storm events are covered, how your deductible applies, and whether your roof is insured at actual cash value or replacement cost. If the coverage falls short, we compare options from other carriers so you can close the gap before you need it.
How much does a new roof increase value
A new roof can raise a home’s value by reducing buyer risk, improving curb appeal, and signaling that major maintenance has already been taken care of. Many homeowners recover a significant portion of their investment because buyers place a high priority on roof condition during inspections, and newer roofs often help homes sell faster and closer to asking price. The exact value increase depends on the age of the existing roof, market demand, and the materials chosen, but replacing a worn or visibly damaged roof typically delivers the strongest return. For sellers in competitive neighborhoods, a new roof can also differentiate their listing by removing one of the most common deal-breakers unexpected repair costs.
Takeaways
Protecting your home from storms requires both preparation and the right roof insurance coverage. A roof that is inspected regularly, reinforced at its weak points, and kept clear of debris has a much better chance of withstanding severe weather. Pairing these preventive measures with a clear understanding of your insurance policy ensures you are financially protected if damage occurs.
The claims process can be stressful, but staying organized and avoiding common mistakes keeps repairs moving forward without unnecessary delays. FarmerBrown Insurance provides the guidance to make each step simpler, from knowing what is covered to comparing options from multiple carriers.
Now is the time for homeowners to review their current setup. Check your roof’s condition, confirm your policy details, and create a plan for what to do when a storm arrives. Small, proactive steps today will protect your home and reduce costly surprises in the future.
Storm Roof Insurance FAQs
Policies typically cover sudden storm damage such as wind, hail, or falling debris. They usually exclude normal wear and tear, and insurers may reduce or deny payment if the roof is near the end of its life or was not maintained.
Actual cash value subtracts depreciation from the settlement. Replacement cost coverage pays for a new roof of similar quality without that deduction.
Check for damage from the ground instead of climbing onto a wet roof, take clear photos of all visible damage, save receipts for temporary fixes like tarps or plywood, and contact your insurance company promptly.
It usually does. A new roof reduces buyer risk, improves curb appeal, and shows that major maintenance is done. The exact increase depends on the age of the old roof, market demand, and the materials chosen.